How overseas buyers can purchase property in Dubai: a step-by-step guide
Overview: is Dubai right for you?
Dubai permits overseas buyers to own property in designated areas; many international purchasers find the market attractive for investment and lifestyle reasons. Before committing, clarify your objectives—long-term residence, rental income, capital growth, or a holiday home—as this will shape the type of property, location, and finance needed.
Because regulations, fees and ownership zones can change, always confirm current requirements and any limits with the Dubai Land Department (DLD) or the Real Estate Regulatory Agency (RERA), and get bespoke advice from a qualified advisor.
Step 1 — research and budget planning
Start by researching neighbourhoods, property types (apartments, villas, townhouses) and whether you need freehold or leasehold ownership. Look at rental yields, occupancy rates and the track record of developers in the areas you’re considering.
Set a realistic budget that includes the purchase price plus transaction costs such as registration or transfer fees, agent commission, potential mortgage fees, NOCs or service-charge arrears, and ongoing running costs. For any specific fee estimates, consult DLD, RERA or a licensed broker.
Step 2 — assemble your professional team
Good local expertise reduces risk. At minimum, engage a RERA-registered real estate agent or brokerage experienced with international clients, a mortgage broker or bank contact if you plan to finance the purchase, and a qualified lawyer if you require contract review or legal structuring.
Also consider a tax advisor in your home jurisdiction to understand cross-border tax implications, and a trusted property manager if you will rent the property or cannot be on-site regularly.
Step 3 — due diligence on property and developer
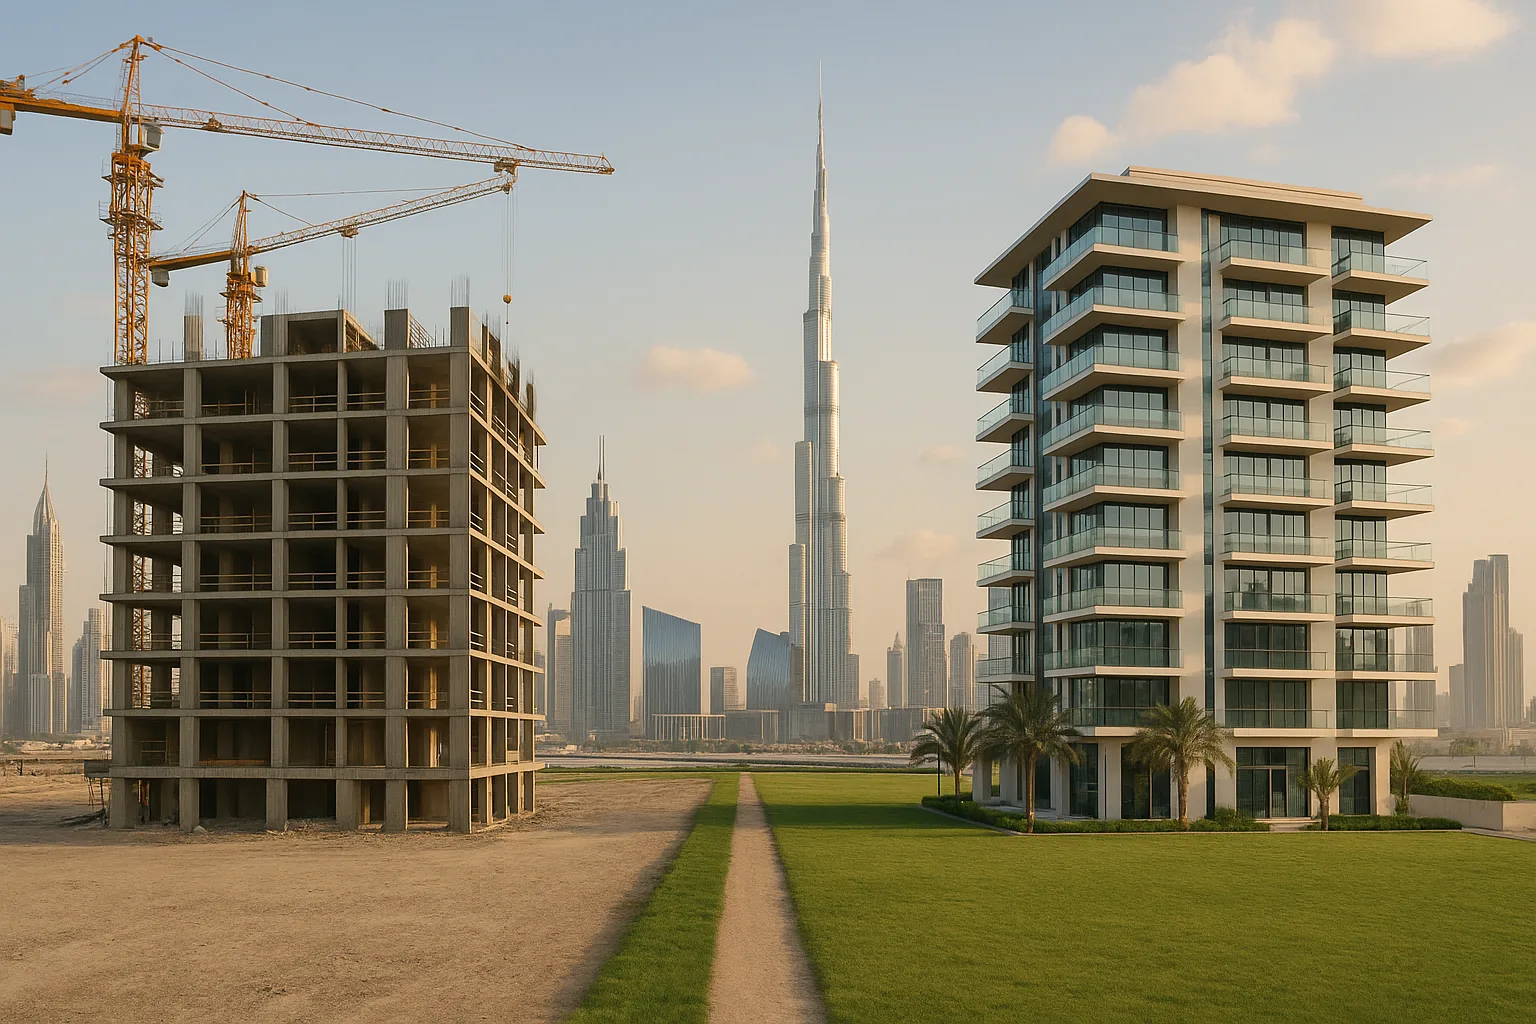
Before making an offer, verify the property's legal status with the Dubai Land Department. Ensure the title deed is clear of encumbrances and that the seller or developer has a clean ownership history. If buying off-plan, confirm the developer's track record for delivery and whether the project is protected by an escrow or other buyer-protection mechanism.
Check service-charge history and any outstanding maintenance liabilities, community rules, and whether there are restrictions on short-term rentals if rental income is part of your plan. Ask for copies of relevant documents and confirm everything through your agent or lawyer.
Step 4 — offer, reservation and contracts
When you’re ready to proceed, your agent will usually submit an offer and, if accepted, you will sign a reservation form and pay a reservation deposit. The reservation protects the property from other buyers while contracts are prepared.
The formal next step is the Sale and Purchase Agreement (SPA) or off-plan contract. Read the SPA carefully or have a lawyer review it—check payment schedule, completion date, handover conditions, developer guarantees, and penalties for delays or breaches. Ensure all agreed inclusions and fixtures are specified in writing.
Step 5 — financing, currency and remote purchase options
If you need a mortgage, obtain pre-approval so you understand lender requirements and affordability. Foreign buyers can access mortgages from UAE banks and some international lenders; terms and documentation will vary, so compare options before committing.
Opening a UAE bank account simplifies payment and transfer processes but isn’t always mandatory; confirm requirements with your bank and legal advisor. If you cannot be present to sign documents, a notarised Power of Attorney (POA) accepted by local authorities can allow an appointed representative to complete the transaction—ensure the POA is tightly drafted and limited in scope.
Step 6 — transfer of ownership and registration
Finalising the purchase normally involves settling all payments, obtaining required No Objection Certificates (NOCs) from the developer or relevant community, and registering the transfer at the Dubai Land Department or the relevant land registry office. The final title deed (commonly known as the 'mulkiya') demonstrates your ownership once the transfer is complete.
Retain copies of all receipts, stamped contracts and the new title deed. Confirm actual fees and the procedural steps directly with DLD or your agent, as administrative requirements can change.
Step 7 — after completion: utilities, management and compliance
Once you own the property, arrange utilities, service accounts and, if required, tenancy registration (for rentals). Check community rules and register with any homeowners’ association where applicable. If you plan to rent, set up a management plan for tenant screening, maintenance and bill collection.
Keep on top of annual service charges and local compliance such as property maintenance standards. Seek professional advice about ongoing tax reporting obligations in both the UAE and your home country.
Practical tips and final considerations
Use licensed professionals—RERA-registered agents, regulated banks and accredited lawyers—to reduce risk. Verify identities and documentation for all parties involved, and insist on written confirmations for any verbal promises.
Before you sign anything, ask your advisor to outline all fees, timelines and retirement of liabilities so there are no surprises. Whenever rules, fees or figures matter, check with the Dubai Land Department, RERA or a qualified legal/financial advisor for the most current and binding information.
Frequently asked questions
Can foreigners buy property in Dubai?
Yes. Foreigners can buy property in designated areas in Dubai. Ownership types and available zones can vary, so confirm current options with the Dubai Land Department and consult a local agent or lawyer for guidance.
Do I need to live in the UAE to buy property?
No, residency is generally not required to purchase property. Many overseas buyers complete purchases remotely via a Power of Attorney. Always check the precise procedural and notarisation requirements with your lawyer and the relevant authorities.
Do I need a UAE bank account to buy?
A UAE bank account makes transactions and mortgage arrangements easier but may not be strictly required for all purchases. Requirements vary between banks and developers—confirm with your bank and advisors.
Can I buy off-plan (pre-construction)?
Off-plan purchases are common, but they carry specific risks and procedures. Verify the developer’s track record, contractual protections, escrow arrangements and delivery guarantees. Have contracts reviewed by a lawyer and confirm regulatory protections with DLD/RERA.
What ongoing costs should I expect after purchase?
Ongoing costs typically include service charges, utilities, insurance, and any mortgage repayments. Exact amounts and payment schedules vary—ask for historical service-charge statements and check with your agent or community management.