Off‑plan versus ready property in Dubai: how to choose
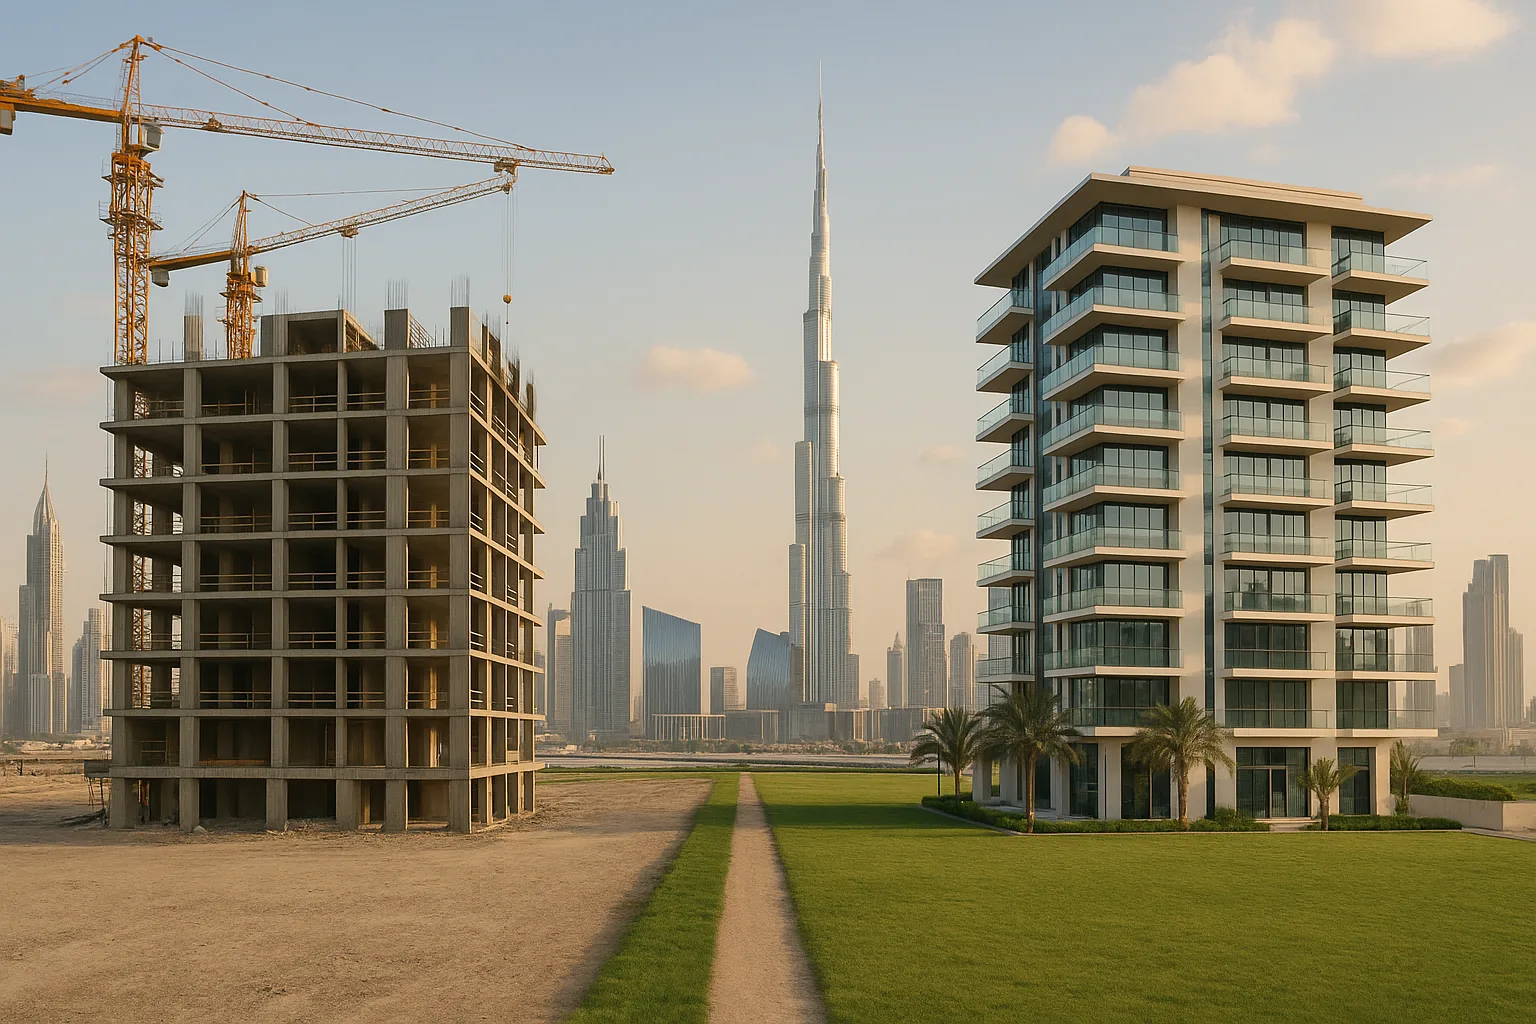
Understand the fundamental differences
Off‑plan properties are sold prior to or during construction; buyers commit early, often via staggered payment plans. Ready properties are completed and available for immediate occupation or rental.
The choice affects timeline, cash flow and what you can inspect before purchase. Off‑plan can offer greater customization and phased payments. Ready stock gives visibility of the final product and immediate control of the asset.
Understanding these core differences will help you prioritise what matters to you: potential price appreciation and customization (off‑plan) versus certainty and immediate income (ready).
Financial considerations and payment structure
Assess your budget and financing needs. Off‑plan transactions typically allow smaller initial deposits and staged payments linked to construction milestones, which may help cash flow. Ready properties usually require a larger upfront outlay and full mortgage approval before transfer.
Factor in ongoing costs that apply to both options: service charges, maintenance, property management and any applicable transfer or registration fees. Never rely on a single number—confirm all fees with your lender, the Dubai Land Department (DLD) and your financial advisor.
How to compare total cost of ownership
- Calculate the full purchase cost: deposit, balance payments, transfer fees and any agency or legal fees. For off‑plan purchases, include all scheduled milestone payments until handover.
- Add recurring costs: annual service charges, utilities, insurance and property management fees. Ask the developer or managing agent for recent service charge budgets for the project when comparing.
- Consider finance costs: interest rates, arrangement fees and how payments are scheduled. For off‑plan purchases, confirm whether interest accrues on staged payments or only after mortgage drawdown.
If you’re comparing two properties, build a multi‑year cash‑flow model (even a simple spreadsheet) that shows when payments are due and projected rental income or expenses. This highlights potential liquidity pressures and helps identify which option aligns with your cash flow tolerance.
Risk profile and due diligence
Off‑plan carries specific risks: construction delays, changes to the specification, developer financial stress, or differences between marketing materials and the finished build. Ready properties remove construction risk, but you should still check for defects, outstanding charges or legal encumbrances.
Due diligence steps to take: verify the developer’s track record and any completed projects; check that the project and sale are registered with relevant authorities (confirm procedures with RERA/DLD); review the sales contract carefully for handover timelines, compensation clauses and escrow arrangements; and obtain independent legal advice where needed.
Practical checks for off‑plan purchases
- Visit other completed developments by the same developer to inspect build quality and after‑sales service.
- Confirm that an escrow account or equivalent statutory protection is in place for buyer funds; ask for documentation.
- Review the master community plan and any proposed future phases which might affect views, access or amenity provision.
- Check the developer’s communications regarding delays and their compensation policy—ensure it is clearly stated in the sales contract.
Practical checks for ready properties
- Commission an independent snagging or building inspection to identify defects or maintenance needs before handover.
- Request a history of service charges and any planned major works that could trigger special assessments.
- Ask for a current occupancy or rental schedule if the property is sold tenanted, and verify the terms of any existing tenancy agreement.
Investment objectives and time horizon
Align the choice with your goals. If you seek capital growth and are comfortable waiting, off‑plan can offer the potential for appreciation from launch to completion. If reliable rental income or immediate occupation is the priority, a ready property is usually the better fit.
Consider exit options and liquidity. Ready properties can be leased or sold immediately, subject to market conditions. Off‑plan holdings may be harder to exit before completion and can be sensitive to market sentiment around handover.
How to assess returns
- For rental investors, calculate gross and net yields: expected rental income divided by acquisition cost (and then subtract running costs to estimate net yield). Use conservative rental estimates and allow for void periods between tenants.
- For capital growth, consider location fundamentals: transport links, planned infrastructure, employment hubs and the developer’s reputation. Capital growth is inherently uncertain—always run downside scenarios in your model.
Practical buying steps: what to check on completion and handover
For off‑plan, build a checklist for snagging: ensure specifications match the contract, inspect finishes and obtain all warranties and certificates before making the final payment. Confirm that the developer has fulfilled statutory requirements and that ownership transfer can proceed through the DLD or the Oqood process—verify the correct procedure with an advisor.
For ready properties, commission an independent inspection, request a history of service charges and confirm there are no outstanding dues. Check that title documentation is clean and that transfer procedures are clear with the seller and your conveyancer.
Handover practicalities
- Arrange for a professional inspection that tests plumbing, electrics, doors and windows, and that checks for water ingress, damp or structural issues.
- Obtain all keys, access cards and appliance manuals. For off‑plan, ensure that warranties for appliances, fixtures and structural elements are provided and clearly dated.
- Secure a complete handover package: title documents, completion certificate or occupancy permit (if applicable), community rules and service charge details.
Negotiation and contract tips
- For off‑plan: negotiate payment milestones, reservation fee amounts and any extra clauses around specifications or handover compensation. Ask about incentives like payment plans, cashback or rental guarantees, but verify the terms in writing.
- For ready stock: insist on a clear inventory where applicable and negotiate for remedial work to be completed before transfer, or obtain a price adjustment to cover identified defects.
- Always include a clear list of conditions in any offer: financing contingency, satisfactory inspection and clean title. Use an independent lawyer to draft or review clauses to avoid unfavorable contractual obligations.
When to choose off‑plan vs ready: scenarios
- Choose off‑plan if you have a medium‑to‑long time horizon, you prioritise capital growth or you value design customisation and flexible payment plans. Off‑plan can be suited to investors prepared to hold through construction and handover.
- Choose ready if you need immediate rental income, want to move in quickly or prefer certainty on product and finishes. Ready homes suit buyers using mortgage financing tied to a completed title deed or those prioritising low execution risk.
Scenario examples (hypothetical guidance)
- A long‑term investor seeking exposure to a new district may accept off‑plan timing and then either retain the property for capital appreciation or re‑let after completion if market conditions are favourable.
- A tenant‑owner needing to relocate for work and requiring immediate accommodation will typically prioritise ready stock for speed and certainty.
Frequently asked questions
How do payment plans differ between off‑plan and ready properties?
Off‑plan purchases commonly include staged payments tied to construction milestones, which can help cash flow. Ready property purchases usually require larger upfront payments or a mortgage approved against a completed title deed. Confirm exact payment schedules and terms with the developer and your lender.
What are the most common risks with off‑plan purchases?
Key risks include construction delays, changes to the project specification, developer insolvency, and market fluctuations affecting resale value. Mitigate these risks by researching the developer’s history, checking project registration with authorities and ensuring escrow protections are in place.
Can I get a mortgage for an off‑plan property?
Mortgage availability and terms for off‑plan properties vary by lender and depend on the developer and stage of construction. Some lenders offer progress‑based financing, but requirements differ—speak to mortgage providers and confirm eligibility and conditions before committing.
What should I check at handover for a ready property?
At handover, have an independent inspection carried out, verify that all fixtures and fittings match the contract, request a statement of service charges and confirm there are no outstanding payments or legal issues on title. Use a conveyancing professional to manage the transfer and registration process.
Who should I consult before making a purchase decision?
Engage a registered real estate broker, an independent lawyer experienced in Dubai property law, and a mortgage advisor if financing is required. Confirm legal and regulatory matters with the Dubai Land Department (DLD) and RERA to ensure compliance with current rules.
Final checklist before you sign
- Verify project registration and developer track record.
- Confirm payment schedule and escrow or protection of funds.
- Obtain pre‑contract legal advice and have all clauses explained.
- Model cash flow for purchase and ownership periods, including worst‑case scenarios.
- Arrange independent inspections at handover and secure all warranties and completion documents.
Choosing between off‑plan and ready property in Dubai comes down to matching timing, risk appetite and financial planning to your objectives. When in doubt, take time to run scenarios with your advisor team and confirm regulatory and finance details with the relevant authorities before signing any contract.